Navigating the "Adulting" Gap: Financial Resilience and Debt Recovery in Modern New England
HARTFORD, CT – As they approach their tenth anniversary this November, Brian and Michael, both 34, represent a growing demographic of professional couples who, despite earning a six-figure household income, find themselves grappling with the psychological and financial weight of consumer debt and the elusive dream of homeownership.
Living in a refurbished industrial mill in central Connecticut with their two cats, the couple’s story is a microcosm of the "middle-class squeeze" affecting millennials in high-cost-of-living corridors. With a combined gross income of over $167,000, the couple feels "behind" their peers—a sentiment fueled by a recent period of housing instability, unexpected medical expenses, and a history of cyclical debt.

Main Facts: The Balance Sheet of a Public Service Household
The financial profile of Brian and Michael is one of high potential tempered by immediate liabilities. Brian serves as a quality assurance manager for a state-run hospital, while Michael works as a project coordinator for a state behavioral health agency, supplemented by a secondary role as a disability leadership coordinator.
Income Summary:
- Total Gross Household Income: $167,544
- Total Net (Take-Home) Income: $109,455
- Current Debt Load: $28,259 (Primarily high-interest consumer credit)
- Total Assets: $91,250 (Largely concentrated in retirement accounts)
Despite a healthy top-line income, the couple’s net liquidity is strained. Their current lifestyle costs approximately $96,414 annually, leaving a theoretical surplus of roughly $13,000. However, the "felt" reality for the couple is one of scarcity, driven by a $2,000 monthly rent and significant "leakage" in discretionary spending areas such as gifts, home goods, and personal care.
Chronology: From Stability to the 2023 Scramble
The couple’s current financial anxiety is rooted in a turbulent eighteen-month window beginning in late 2022. For eight years, Brian and Michael enjoyed the low-overhead stability of a 600-square-foot studio apartment priced at $945 per month. This "cozy" arrangement allowed them to forecast a home purchase in late 2023.
However, the volatility of the post-pandemic rental market and unforeseen life events disrupted this trajectory:
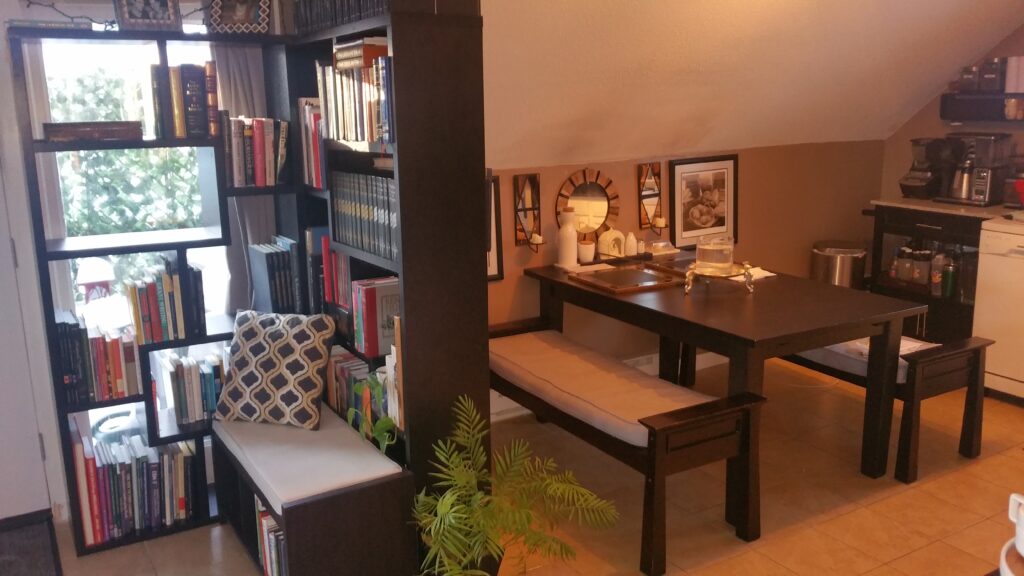
- Housing Uprooting: In early 2023, the couple was forced to navigate a predatory rental market, spending 3.5 months "scrambling" to find a new residence. They eventually transitioned to a luxury two-bedroom apartment in a refurbished mill. While the move provided much-needed space and professional "age-appropriateness," it more than doubled their housing costs to $2,000 per month.
- Veterinary Crisis: Simultaneously, the couple adopted two kittens who suffered from chronic gastrointestinal issues, leading to significant unplanned veterinary expenses and specialized dietary costs that now average $517 per month.
- Career Transition: Brian moved from the private non-profit sector to a state government role. While this move secured "healthcare for life" and a pension, the transition period, combined with the move, led to a reliance on credit cards to bridge the gap.
By mid-2023, the couple found themselves in their current "luxurious" but debt-burdened state, feeling that their goals of marriage, business ownership, and "leaving a legacy" were slipping out of reach.
Supporting Data: The Anatomy of the Debt and Asset Portfolios
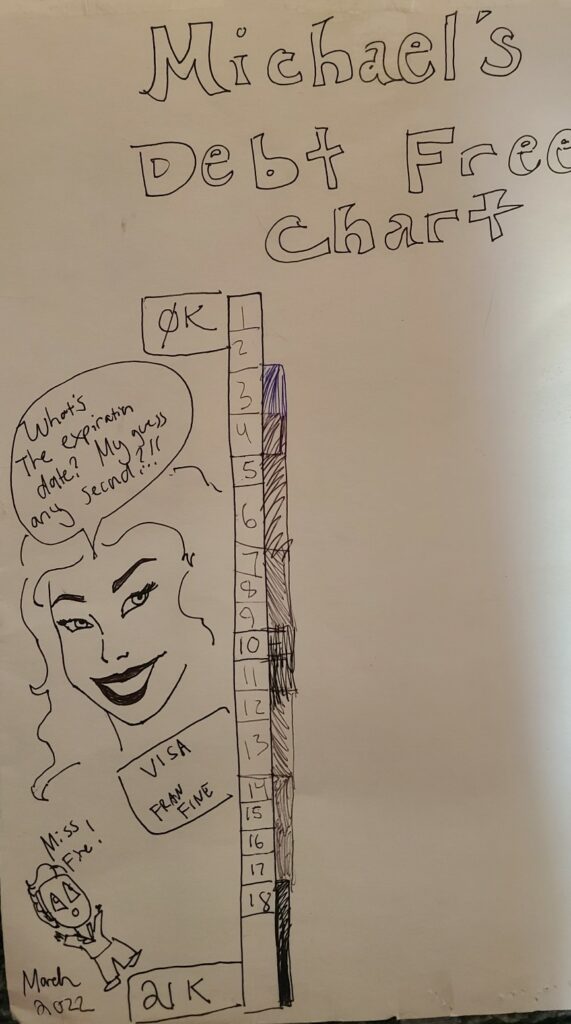
To understand the couple’s path forward, analysts point to the specific structure of their liabilities. The $28,259 debt is not a monolith; it is a ticking clock of interest rates.
The Debt Breakdown
- Brian’s SCU Visa: $16,057 (0% interest until November 2023, then 17.99%)
- Michael’s Visa Platinum: $9,700 (10.99% interest)
- Brian’s Navy Federal Visa: $2,503 (0.99% interest until November 2023, then 17.74%)
The looming "November Cliff"—where over $18,000 of debt will transition from near-zero to high-double-digit interest—represents the most pressing threat to their financial stability.
The Asset Breakdown
Conversely, the couple’s asset side shows remarkable strength in long-term vehicles, thanks to their public sector roles:
- Retirement Accounts: $76,920 (Combined 401k, 403b, 457, and Pension funds)
- Liquid Cash: $9,000 (Combined savings and emergency funds)
- Health Savings: $5,193 (Combined HSAs)
The data suggests a "wealth paradox": the couple has nearly $100,000 in net worth but lacks the liquidity to handle a major car repair or a job loss without resorting to further debt. Brian’s 2007 Mercedes and Michael’s 2007 Subaru, both with 175,000 miles, represent a looming "expected emergency" as maintenance costs for the Mercedes have averaged over $1,000 monthly in recent periods.
Official Responses: Strategic Recommendations for Recovery
Financial experts, including Elizabeth Willard Thames (known as "Liz Frugalwoods"), have reviewed the case, offering a "judgment-free" roadmap to transition the couple from debt-cycles to wealth-building.
1. The "Austerity Sprint"
The primary recommendation is a radical, short-term reduction in spending to beat the November interest rate hike. By categorizing expenses into "Fixed," "Reduceable," and "Discretionary," the analysis suggests the couple could slash monthly spending from $8,035 to $6,665.
- Impact: This would allow for a debt-repayment velocity of $4,456 per month.
- Timeline: At this rate, the couple could be entirely debt-free in approximately 6.5 months, effectively neutralizing the 17.99% interest threat.
2. The Retirement "Triple Crown"
The analysis highlights Brian’s unique access to a 403b, a 457b, and a state pension. Experts advise that once the consumer debt is eliminated, the couple should prioritize maxing out these tax-advantaged accounts. The 457b plan, in particular, is noted for its flexibility, allowing for penalty-free withdrawals upon leaving an employer, regardless of age—a key tool for their goal of "starting a business" later in life.
3. The Graduate School ROI Test
Regarding Brian’s desire to pursue a Master’s degree, the professional recommendation is conservative: education should only be pursued if there is a "guaranteed, iron-clad correlation" to a significant salary increase. In the current economic climate, taking on student debt for "academic success" or "personal fulfillment" is viewed as a high-risk detour from their goal of homeownership.
Implications: The Psychological and Social Cost of Financial Shame
The case of Brian and Michael illuminates a broader social issue: the "shame" associated with perceived financial failure among high-earning millennials. Both partners expressed feelings of being "behind" their peers and a source of "disappointment" to their families.
The "Adulting" Illusion
Liz Frugalwoods notes that Brian’s perception—that everyone else has it "together"—is often a byproduct of social comparison rather than financial reality. "A lot of people his age have the goal to achieve what he and Michael already have: stable, high-paying jobs, a ten-year committed relationship, and significant retirement contributions," Thames noted.
The Cycle of "Feast and Famine"
The broader implication of the couple’s struggle is the danger of the "debt-payoff-debt" cycle. Without a fundamental shift in how they view discretionary spending, there is a risk that the "famine" period of debt repayment will lead to a "feast" of compensatory spending later.
To break this, the couple must transition from "tracking" to "mindful allocation." The move from a $945 studio to a $2,000 luxury apartment was a choice for "age-appropriateness," but it reduced their financial margin for error. The path to homeownership in Connecticut’s rural market—their ultimate goal—will require them to reconcile their desire for "treasures" and luxury rentals with the cold math of a down payment.
Conclusion: A Path to the "Next Level"
Brian and Michael are not in a financial crisis; they are in a liquidity crunch. With a household income in the top 15-20% of American households, their "spreadsheet problems" are solvable through discipline rather than drastic life changes.
By neutralizing their high-interest debt by the end of 2023, building a robust six-month emergency fund, and leveraging Brian’s state benefits, the couple can move from a state of " ड्रीम्स डेफ़र्ड" (dreams deferred) to one of legacy building. The "next level of adulting" they seek is not found in a master’s degree or a luxury apartment, but in the peace of mind that comes from a $0 balance and a growing down payment fund.