The Micro-Economy of Childhood: How Early Financial Literacy is Reshaping Modern Parenting
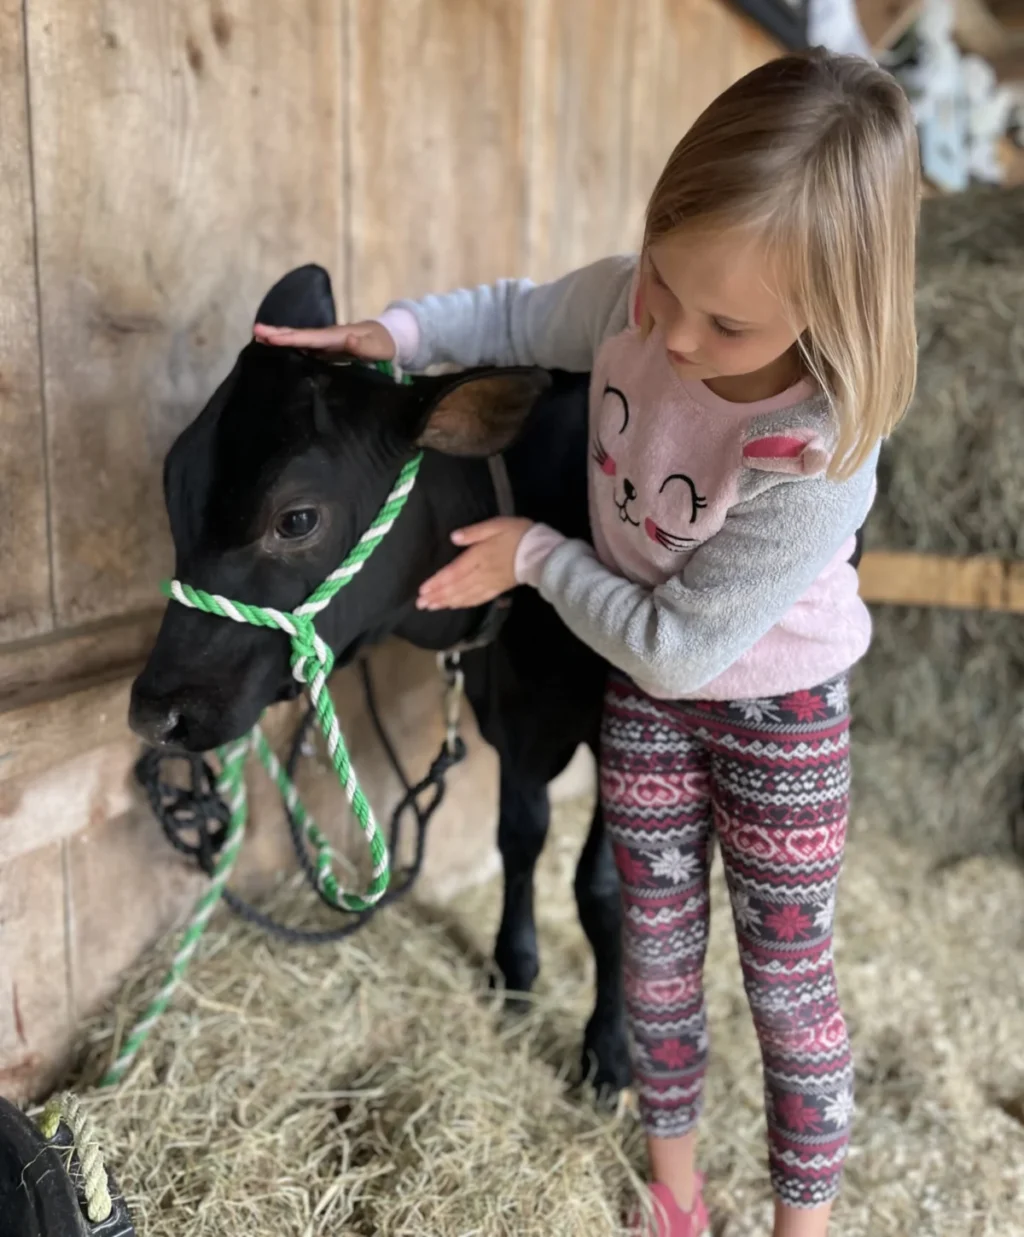
VERMONT – In the rolling hills of rural Vermont, a social and educational experiment is quietly unfolding within the confines of a family home. While most children aged five and seven are focused on the whimsy of summer fairs and the tactile joy of farm animals, two young sisters—pseudonymously known as Kidwoods and Littlewoods—are navigating the complex realities of labor, debt, and discretionary spending.
This family’s approach to financial education represents a growing movement among parents to demystify the "invisible" nature of modern money. By transforming everyday experiences, such as the local county fair, into high-stakes lessons in economics, these parents are attempting to build a "financial scaffold" designed to support their children through an increasingly complex consumer landscape.
Main Facts: The Family Money Philosophy
At the heart of this educational model is a clearly defined "Family Money Philosophy." Unlike traditional allowance systems, which often provide a flat weekly rate regardless of behavior or effort, this model distinguishes sharply between "needs" and "wants."

The parental units provide for all essential "needs," which include housing, healthcare, clothing, education, and admission to cultural venues like museums and fairs. However, "wants"—defined as souvenirs, specialized treats, and items from the Scholastic Book Fair—must be funded entirely by the children’s own earnings.
The system is built on four primary pillars:
- Demystification: Explicitly explaining that money is a direct result of labor.
- Labor-Based Earnings: Providing a "chore economy" where tasks are paid at a fair market value.
- Autonomous Responsibility: Requiring children to manage their own physical currency and remember to bring it to venues.
- Experiential Consequences: Allowing children to experience the "sting" of debt and the regret of impulse spending in a safe environment.
Chronology: From Observation to Autonomy
The evolution of this financial curriculum has moved through several distinct phases, tracking the developmental stages of the children involved.
Phase I: The Demystification of Labor
The process began with simple observation. The parents took deliberate steps to explain the "boring" nature of their professional lives. By allowing the children to observe remote work meetings and explaining that "Mama works and is paid money for her work," they bridged the gap between the household’s resources and the effort required to secure them. This phase was designed to remove the "magic" from the ATM and the grocery store checkout.
Phase II: The Implementation of the Chore Economy
Once the concept of "work for pay" was established, the family introduced a rotating list of paid chores. These tasks are distinct from "Family Citizenship" duties—such as clearing one’s own plate or making one’s bed—which remain unpaid. Paid chores include tasks that benefit the entire household, such as organizing kitchen cabinets, emptying communal trash cans, or assisting with seasonal farm maintenance. Notably, the system allows for negotiation; the seven-year-old recently brokered a $10 "lump sum" deal for a comprehensive kitchen reorganization.
Phase III: The "Unicorn" Debt Crisis
A pivotal moment occurred at a previous year’s county fair. The elder child desired an inflatable turquoise unicorn priced at $13, while possessing only $9. The parents allowed the child to go into debt, lending the remaining $4 under the condition of mandatory future labor. The subsequent "debt service"—working for an hour at home without receiving any immediate cash—led to a visceral realization. The child noted, "It is not fun to do chores to earn money for something I’ve already bought." This experience effectively halted all requests for credit for the following calendar year.
Phase IV: Collaborative Spending and Planning
Most recently, the children have begun to apply logic to their shared consumption. During local farm "pizza nights," the children realized that splitting the cost of a $7 dessert was more efficient than one sibling bearing the full cost for a shared treat. This phase introduced the complexities of dividing odd numbers and the necessity of planning ahead for "spending sojourns."
Supporting Data: The Mechanics of the Household Market
The success of this model relies on a structured list of chores that rotate based on the season and the child’s ability. According to the family’s internal records, the "market rates" for labor are strictly enforced. A job is only considered complete if it is done to a professional standard; for instance, spilling trash during the emptying process requires the "trashlettes" to be picked up individually before payment is rendered.
Paid Chore Examples & Market Rates:
- Kitchen Organization: Negotiable (up to $10 for large-scale projects).
- Communal Trash Management: Standardized per-unit rate.
- Garden/Farm Maintenance: Seasonal rates based on difficulty.
- Laundry Services: Only paid if processing a parent’s laundry, not the child’s own.
The "Citizenship" vs. "Labor" Divide:
The parents maintain a strict boundary to ensure children do not expect payment for basic self-care.
- Unpaid (Family Citizenship): Collecting eggs, composting, cleaning one’s own room, clearing the table.
- Paid (Professional Labor): Tasks that would otherwise require parental time or external hiring.
Official Responses: Expert Perspectives on Early Financial Autonomy
While the Vermont family’s approach is individual, it aligns with emerging theories in developmental psychology. Financial educators suggest that "scaffolding"—the process of providing a support structure that is gradually removed as a child gains competence—is the most effective way to prevent financial anxiety in adulthood.
"By allowing a child to experience the ‘pain’ of debt for a four-dollar plastic unicorn, these parents are providing a low-stakes vaccination against the high-stakes debt of adulthood," says Dr. Elena Rossi, a fictionalized composite of child development experts. "The goal isn’t to make the child a miser, but to make the money ‘real’ in a world that is increasingly digital and abstract."
However, some critics of labor-for-pay models argue that they may commodify the parent-child relationship. In response, the family emphasizes that money is presented merely as a "tool," comparable to exercise or sleep—a means to an end rather than a measure of self-worth or happiness. The parents maintain that by removing the "mystery" of money, they are also removing the "judgment and bias" often associated with it.
Implications: The Future of the "Bank of Parental Units"
As the children grow, the curriculum is set to become more sophisticated. The next scheduled phase is the opening of the "Bank of Parental Units," a domestic savings program that will introduce the concept of interest.
The Savings Shift:
Currently, the children spend the majority of what they earn. The introduction of a parental-backed interest rate is designed to incentivize delayed gratification. By offering a high "internal" interest rate—far exceeding current market rates—the parents hope to demonstrate the power of compound growth in a way that a five-year-old can comprehend.
Long-term Financial Resilience:
The ultimate implication of this Vermont experiment is the cultivation of "financial agency." By the time these children reach adolescence, they will have a decade of experience in:
- Price Comparison: Evaluating whether a $7 cupcake is worth the labor required to earn it.
- Negotiation: Understanding how to value their own time and effort.
- Logistics: Managing physical assets (wallets) and planning for future events.
In a society where the average American adult carries significant credit card debt and struggles with basic financial literacy, the "Frugalwoods" model offers a proactive alternative. It suggests that the best way to prepare children for the "weird adult world of money" is not to shield them from it, but to give them the tools to navigate its smaller, turquoise-unicorn-sized versions first.
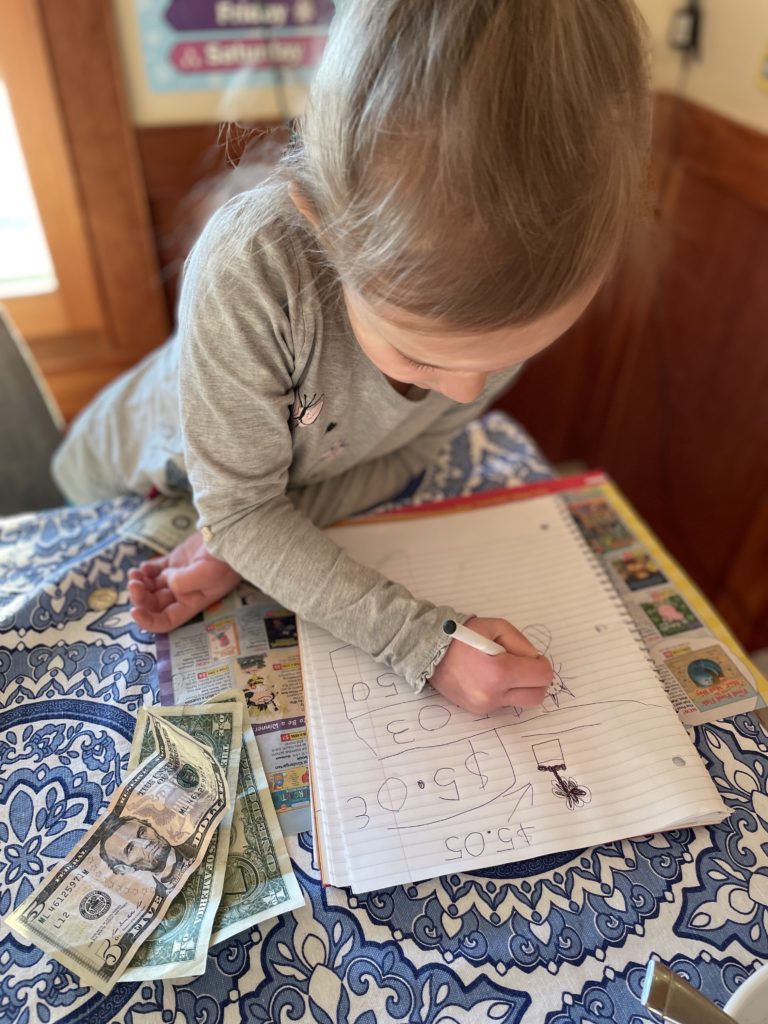
As the elder daughter, Kidwoods, recently wrote in a hand-drawn book about her mother’s job: "Her job is to help other people with their money… the meetings are very boring. But they are really important." While she may find the meetings dull, the seven-year-old has already mastered a lesson many adults never do: that money, while boring in the abstract, is the engine of autonomy in the real world.