From the Barnyard to the Bank: A Comprehensive Analysis of Early Childhood Financial Literacy Strategies
VERMONT – In an era of pervasive digital transactions and "one-click" purchasing, the fundamental mechanics of money are becoming increasingly abstract for the next generation. However, in the rural landscape of Vermont, a burgeoning movement toward "hands-on" financial education is taking root. By utilizing high-pressure consumer environments—such as the traditional county fair—as living classrooms, parents are finding innovative ways to instill fiscal discipline in children as young as five.
Recent observations of the "Frugalwoods" household, a family dedicated to intentional spending and financial independence, provide a case study in how "family money philosophies" can demystify the complexities of the modern economy for young children. By transitioning from passive recipients of parental provision to active participants in a micro-economy, children are learning that money is not an infinite resource, but a tool earned through labor and managed through strategy.
Main Facts: The "Needs vs. Wants" Framework
The foundation of this educational model rests on a binary distinction between essential expenditures and discretionary spending. In the Frugalwoods household, the division is clearly articulated to the children, aged five and seven (referred to as Littlewoods and Kidwoods).
The Parental Obligation (The "Needs")
Under this framework, parents assume full responsibility for "needs," which include:

- Essential Infrastructure: Housing, utilities, and healthcare.
- Nutritional Baselines: All home-prepared meals and basic groceries.
- Educational Materials: Books from libraries and used sales, as well as museum admissions.
- Functional Attire: Necessary clothing and footwear.
The Child’s Responsibility (The "Wants")
Conversely, the children are responsible for "discretionary items." This category is where the majority of financial lessons occur. It includes:
- Premium Consumables: Desserts at restaurants or special snacks at fairs that exceed the provided meal.
- Souvenirs and Trinkets: Items from gift shops or fairground vendors.
- New Media: Books purchased specifically from the Scholastic Book Fair, despite the availability of free library alternatives.
By drawing this line, parents remove the "nag factor" often associated with shopping. The question is no longer "Can I have this?" but rather "Do I have enough of my own money to buy this?"
Chronology: The Evolution of a Micro-Economy
The development of financial literacy in the household has followed a distinct chronological path, moving from simple labor to complex debt management and collaborative purchasing.
Phase I: The Labor Market (Ages 4-5)
The process began with the introduction of "market value" chores. Parents identified tasks that provided a genuine benefit to the family collective—such as organizing kitchen cabinets or cleaning common areas—and offered a set price. This established the primary link between effort and income.
Phase II: The "Unicorn Debt Crisis" (Ages 6)
A pivotal moment occurred during a previous year’s county fair. Kidwoods, then six, desired an inflatable turquoise unicorn priced at $13, but only possessed $9. In a calculated pedagogical move, the parents allowed her to go into debt, lending her the $4 difference.
The aftermath served as a visceral lesson in the "cost" of credit. Upon returning home, Kidwoods was required to perform chores to pay off the balance. The realization that she was working without receiving a new reward—because the "reward" had already been consumed—created a lasting aversion to debt. "It is not fun to do chores to earn money for something I’ve already bought," the child noted, articulating a fundamental truth that many adults struggle to grasp.
Phase III: The Cooperative Model (Present Day)
Most recently, the sisters have moved toward collaborative spending. During local farm pizza nights, the seven-year-old recognized that she was funding a $7 dessert that her younger sister also enjoyed. This led to a negotiation where the cost was split. This phase introduced the complexities of dividing odd numbers (currency denominations) and the social contract of shared expenses.
Supporting Data: The Chore Economy and Wage Structure
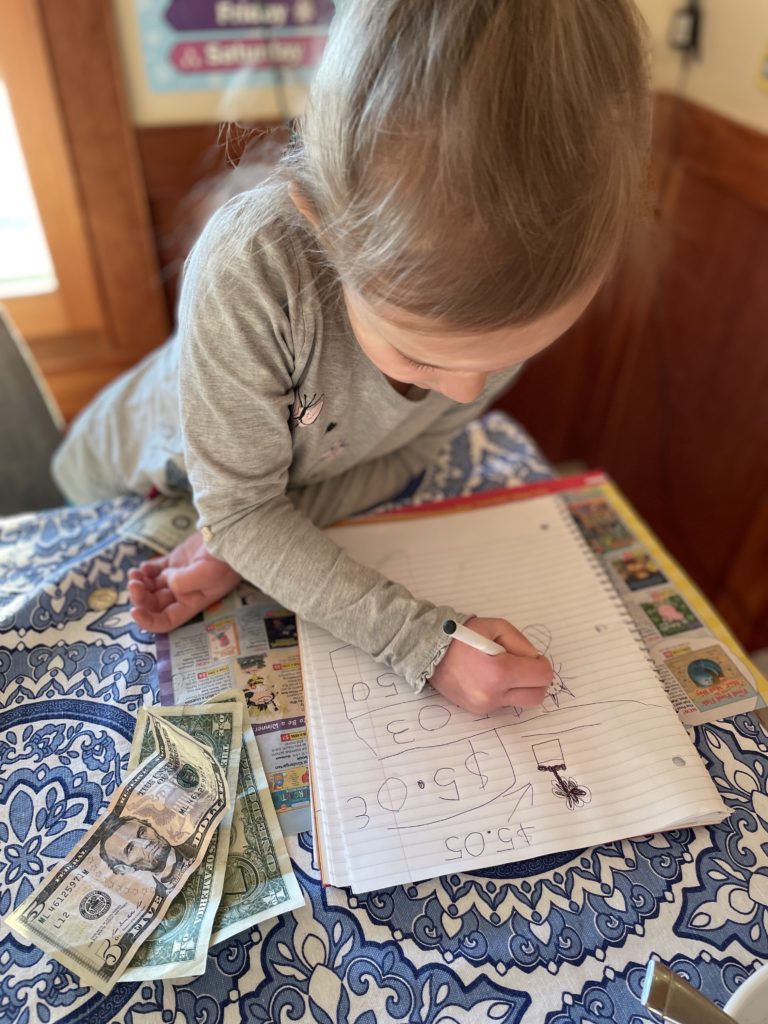
To maintain the integrity of the educational model, the parents utilize a structured wage system. Chores are divided into "Unpaid Daily Work" and "Paid Professional Chores."
The Unpaid Sector (Civic Duty)
Tasks that contribute to the child’s own well-being or the basic maintenance of their environment are unpaid. These are framed as the "cost of entry" for living in a functional family unit.
- Personal Maintenance: Putting away personal laundry, making beds, and cleaning bedrooms.
- Basic Contributions: Clearing the dinner table, collecting eggs from the family chickens, and managing compost buckets.
The Paid Sector (The Labor Market)
Paid chores are those that would otherwise require parental time or external services. These are seasonal and fluctuate based on the child’s ability level. Examples include:
- Organizational Projects: Sorting the "stuffy basket" or organizing kitchen drawers (negotiated at a lump sum, such as $10).
- Maintenance: Emptying house-wide trash cans or assisting in the garden.
The "Quality Control" Clause: A critical data point in this system is the requirement for "minimal adult assistance." If a task is performed poorly—such as spilling trash while emptying bins—the "contract" is not considered fulfilled until the error is rectified. This ensures children understand the relationship between quality of work and the receipt of payment.
Professional Perspectives: Scaffolding and Cognitive Development
While the Frugalwoods approach is a personal family strategy, it aligns with several established pedagogical theories regarding childhood development and financial literacy.
The Concept of "Scaffolding"
The parents describe their method as "scaffolding"—a term popularized by psychologist Lev Vygotsky. By starting with basic concepts like counting coins and reading price tags, they build a foundation before introducing abstract concepts like compound interest or stock market volatility.
Demystifying the "Adult World"
Experts in childhood education often note that children view parental spending as a magical, infinite process. By explicitly stating, "Mama works and is paid money, which she then uses for groceries," the parents are performing a "de-mystification" of the economy. This removes the anxiety and "taboo" surrounding money, replacing it with a factual understanding of cause and effect.
Emotional Regulation and the "Forgotten Wallet"
The household also enforces a "Personal Responsibility" mandate. If a child forgets their wallet when visiting the fair, the parents do not provide a "bailout." While this often leads to temporary emotional distress, it serves as a high-stakes lesson in organization and the physical security of assets. The "near-loss" of a wallet at a museum gift shop, for instance, provided a more effective lesson in asset protection than any lecture could achieve.
Implications: Long-Term Fiscal Health and Autonomy
The implications of this rigorous early-childhood training extend far beyond the borders of a Vermont farm. By treating money as a "tool" rather than a measure of "self-worth or emotional wellness," the parents are insulating their children against the psychological traps of consumerism.
1. Prevention of "Lifestyle Creep"
By forcing children to choose between a $7 cupcake and a future toy, they are developing the "opportunity cost" muscle. This cognitive habit is essential for avoiding the "lifestyle creep" that plagues many high-income earners later in life.
2. The Shift Toward Savings and Interest
The next planned phase for the family is the introduction of the "Bank of Parental Units." By offering interest on saved chore money, the parents intend to transition the children from a "spend-all" mentality to a "wealth-building" mentality. This introduces the concept of "passive income"—money earning money—which is the cornerstone of long-term financial independence.
3. Autonomy and Agency
Perhaps the most significant implication is the sense of agency granted to the children. When a seven-year-old can successfully order, pay for, and receive a product independently, they are gaining more than just a dessert; they are gaining the confidence to navigate a complex society.
In conclusion, the Frugalwoods’ "Family Money Philosophy" suggests that the best time to teach a child about the dangers of debt and the value of labor is not in high school with a first credit card, but in the barnyard with a $13 inflatable unicorn. By allowing children to fail—and succeed—within a controlled environment, parents are equipping them with the ultimate survival tool: financial literacy.
About the Methodology: This report is based on the documented experiences of the Frugalwoods family during the 2023-2024 period. The strategies mentioned are intended for educational purposes and reflect a specific approach to frugal living and intentional parenting.