Financial Resilience and the Path to Homeownership: A Comprehensive Analysis of Mid-Career Debt Management
CONNECTICUT — In an era defined by volatile rental markets and the shifting landscape of social safety nets, many mid-career professionals find themselves at a paradoxical crossroads: earning significant salaries while remaining tethered to consumer debt and the instability of the leasing cycle. A recent deep-dive case study of a Connecticut-based couple, Michael and Brian, provides a quintessential look into the financial mechanics of "High Earners, Not Rich Yet" (HENRYs) as they attempt to pivot from debt-servicing to wealth-building and homeownership.
At 34 years old, both Michael and Brian have established stable careers within the state’s public and behavioral health sectors. However, despite a combined gross household income exceeding $167,000, the couple reports a sense of stagnation, cited primarily as the "shame" of consumer debt and a lack of real estate equity. Their situation highlights a broader national trend where professional success does not always correlate with immediate financial security.

Main Facts: The Financial Profile of a State-Sector Household
The financial health of Michael and Brian is characterized by high earning potential offset by significant monthly expenditures and a recent history of unplanned life events.
Michael serves as a project coordinator for a state behavioral health agency, supplemented by a secondary role as a disability leadership coordinator. His background as a brain injury survivor informs his advocacy work, providing a mission-driven component to his career. Brian operates as a quality assurance manager for a state-run hospital, a role that offers a "triple crown" of public sector benefits: a 403(b), a 457(b) deferred compensation plan, and a state pension.
Income and Asset Breakdown:
- Total Gross Income: Approximately $167,544 per annum.
- Total Net (Take-Home) Income: $109,455 per annum.
- Total Liquid & Retirement Assets: $91,250.
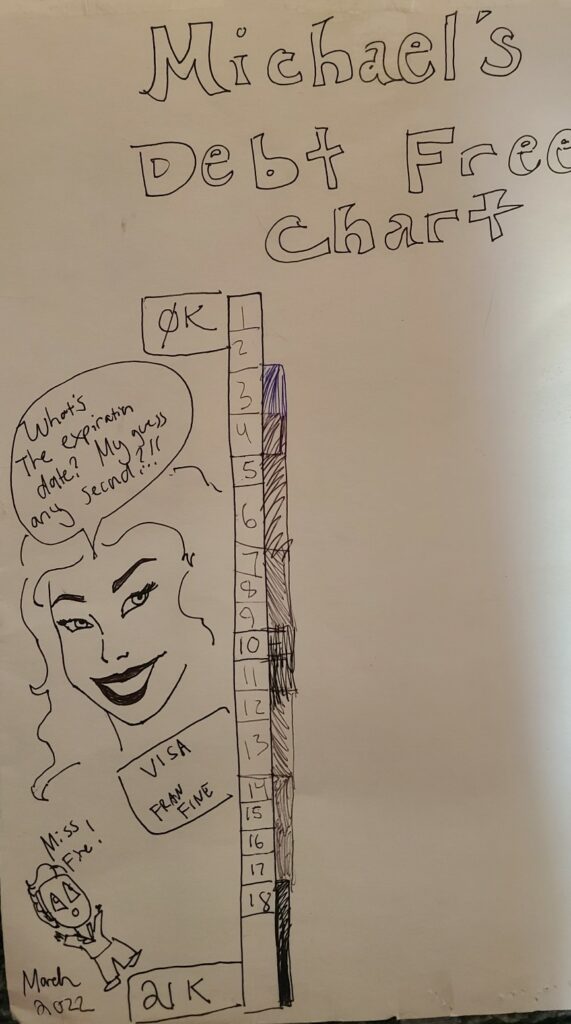
- Total Consumer Debt: $28,259 (primarily across three high-limit credit cards).
The couple’s debt is currently concentrated in low-interest promotional windows. Brian holds a $16,057 balance at 0% interest until November 2023, after which the rate spikes to 17.99%. Michael carries a $9,700 balance at 10.99%, while a third card holds $2,503 at a temporary 0.99% rate. This "interest rate cliff" creates a pressing deadline for their financial restructuring.
Chronology: From Stability to Displacement (2013–2023)
The couple’s current financial anxiety is rooted in a decade-long trajectory that saw significant triumphs followed by a destabilizing 2022-2023 period.
- 2013–2021: The Accumulation Phase. Brian successfully paid off $58,000 in student loans, a major milestone in their early 30s. During this time, they resided in a 600-square-foot studio apartment for $945 per month, allowing for a low cost of living that masked underlying spending habits.
- August 2022: The Catalyst for Change. The couple began planning for homeownership with their cat, Rex. However, the plan was upended by the sudden loss of Rex and the subsequent adoption of two new kittens who required significant veterinary care.
- Early 2023: Housing Displacement. The couple was forced to navigate a ruthless rental market after eight years in their studio. They eventually moved into a refurbished industrial mill apartment in central Connecticut. While the new home offers 12-foot ceilings and professional office space, the rent jumped from $945 to $2,000—a 111% increase in housing costs.
- Present Day: Facing the expiration of 0% interest debt windows, the couple has sought professional financial consultation to bridge the gap between their "treasure" collection (personal belongings) and their goal of "owning the earth" (land and homeownership).
Supporting Data: The Anatomy of a $96,000 Annual Budget
An analysis of the couple’s monthly expenditures reveals a high-burn rate that complicates their ability to save for a down payment. Their annual spending of $96,414 covers both essential living costs and significant discretionary leakage.
Fixed and Semi-Variable Costs
Housing and debt servicing constitute the largest portion of their budget. Rent stands at $2,000, while their current aggressive debt repayment plan allocates $2,000 per month across various cards.
A notable outlier in their budget is vehicle maintenance. Brian’s 2007 Mercedes and 2007 Subaru, while paid off, have incurred an average of $1,064 per month in repairs and fuel over the last eight months. This suggests that the "savings" of not having a car payment are being negated by the maintenance costs of aging luxury and utility vehicles.
Discretionary and "Hidden" Leakage
The couple spends approximately $517 per month on pet-related costs (food, litter, and vet bills), reflecting the high cost of specialized care for their kittens. Other discretionary items include:
- Groceries/Dining Out: $669 total.
- Personal Care/Therapy: $300.
- Gifts/Home Goods: $460.
- Books/Games/Subscriptions: $95.
While these amounts seem manageable in isolation, they contribute to a lifestyle where $13,041 of annual "surplus" net income remains unaccounted for in their current savings trajectory.
Official Consultation: Strategic Recommendations for Debt Eradication
Financial expert Liz Frugalwoods provided a comprehensive audit of the couple’s situation, offering a roadmap to transition from "debt-shame" to "equity-building." The core of the recommendation is a "spending detox" designed to capitalize on their high income.
1. The 6.5-Month Debt Elimination Plan
By reclassifying expenses into Fixed, Reducible, and Discretionary categories, the consultant identified $1,370 in monthly discretionary spending that could be redirected. By pausing spending on eating out, gifts, home goods, and personal care, the couple could increase their monthly debt payment from $2,000 to $4,456. At this accelerated rate, the $28,259 debt would be eliminated in approximately six and a half months, effectively beating the November interest rate hikes.
2. Optimizing the "Triple Crown" of Retirement
Brian’s position as a state employee provides a rare level of retirement security. The consultant recommends:
- The 457(b) Advantage: Prioritizing contributions here because, unlike a 403(b) or 401(k), funds can be withdrawn penalty-free upon leaving the employer, regardless of age. This is a critical tool for their goal of early or flexible retirement.
- HSA Utilization: Maximizing Health Savings Accounts to serve as a secondary "stealth IRA" for long-term medical costs.
3. The Master’s Degree ROI Audit
Addressing Brian’s desire for a graduate degree, the expert advice was strictly utilitarian: pursue the degree only if there is a "guaranteed, iron-clad correlation" to a significant salary increase. In the absence of a direct ROI, the tuition costs would likely represent a "dream deferred" for their homeownership goals.
Implications: The Psychological and Economic Stakes
The case of Michael and Brian reflects a broader societal anxiety regarding the "signifiers of adulthood." Both men expressed profound shame for being "behind" their peers, despite having a six-figure income and robust state pensions. This "comparison trap" is exacerbated by the current economic climate, where high interest rates and low housing inventory make the leap from renting to owning feel insurmountable.
The "Emergency Fund" as a Psychological Buffer:
The consultant emphasized that their current $9,000 cash reserve is insufficient, covering only one month of expenses. For Michael and Brian, a six-month emergency fund is not just a financial requirement but a psychological necessity to end the "debt-payoff-debt" cycle. Without a cash buffer, the next "predictable emergency"—such as a car repair or vet bill—will inevitably land back on a credit card, perpetuating the cycle of shame.
The Connecticut Housing Outlook:
For residents in central Connecticut, the transition to homeownership requires more than just a down payment; it requires a lifestyle shift. The couple’s current "luxurious" mill apartment provides a high quality of life that may be difficult to replicate in a starter home without significant maintenance costs. The implication for Michael and Brian is that they must decide if the "earth to call their own" is worth the "austere famine" required to save for it.
Conclusion
Michael and Brian are not in a financial crisis; they are in a "spreadsheet crisis." With a net income of nearly $110,000 and access to elite retirement vehicles, their path to homeownership is clear but requires a rigorous decoupling of their self-worth from their debt balance. By executing a short-term aggressive payoff and stabilizing their emergency reserves, the couple is positioned to achieve "adulting" milestones that are, in reality, already within their grasp.