The Expat Financial Paradox: Navigating the High-Stakes Return from Vietnam to the United States
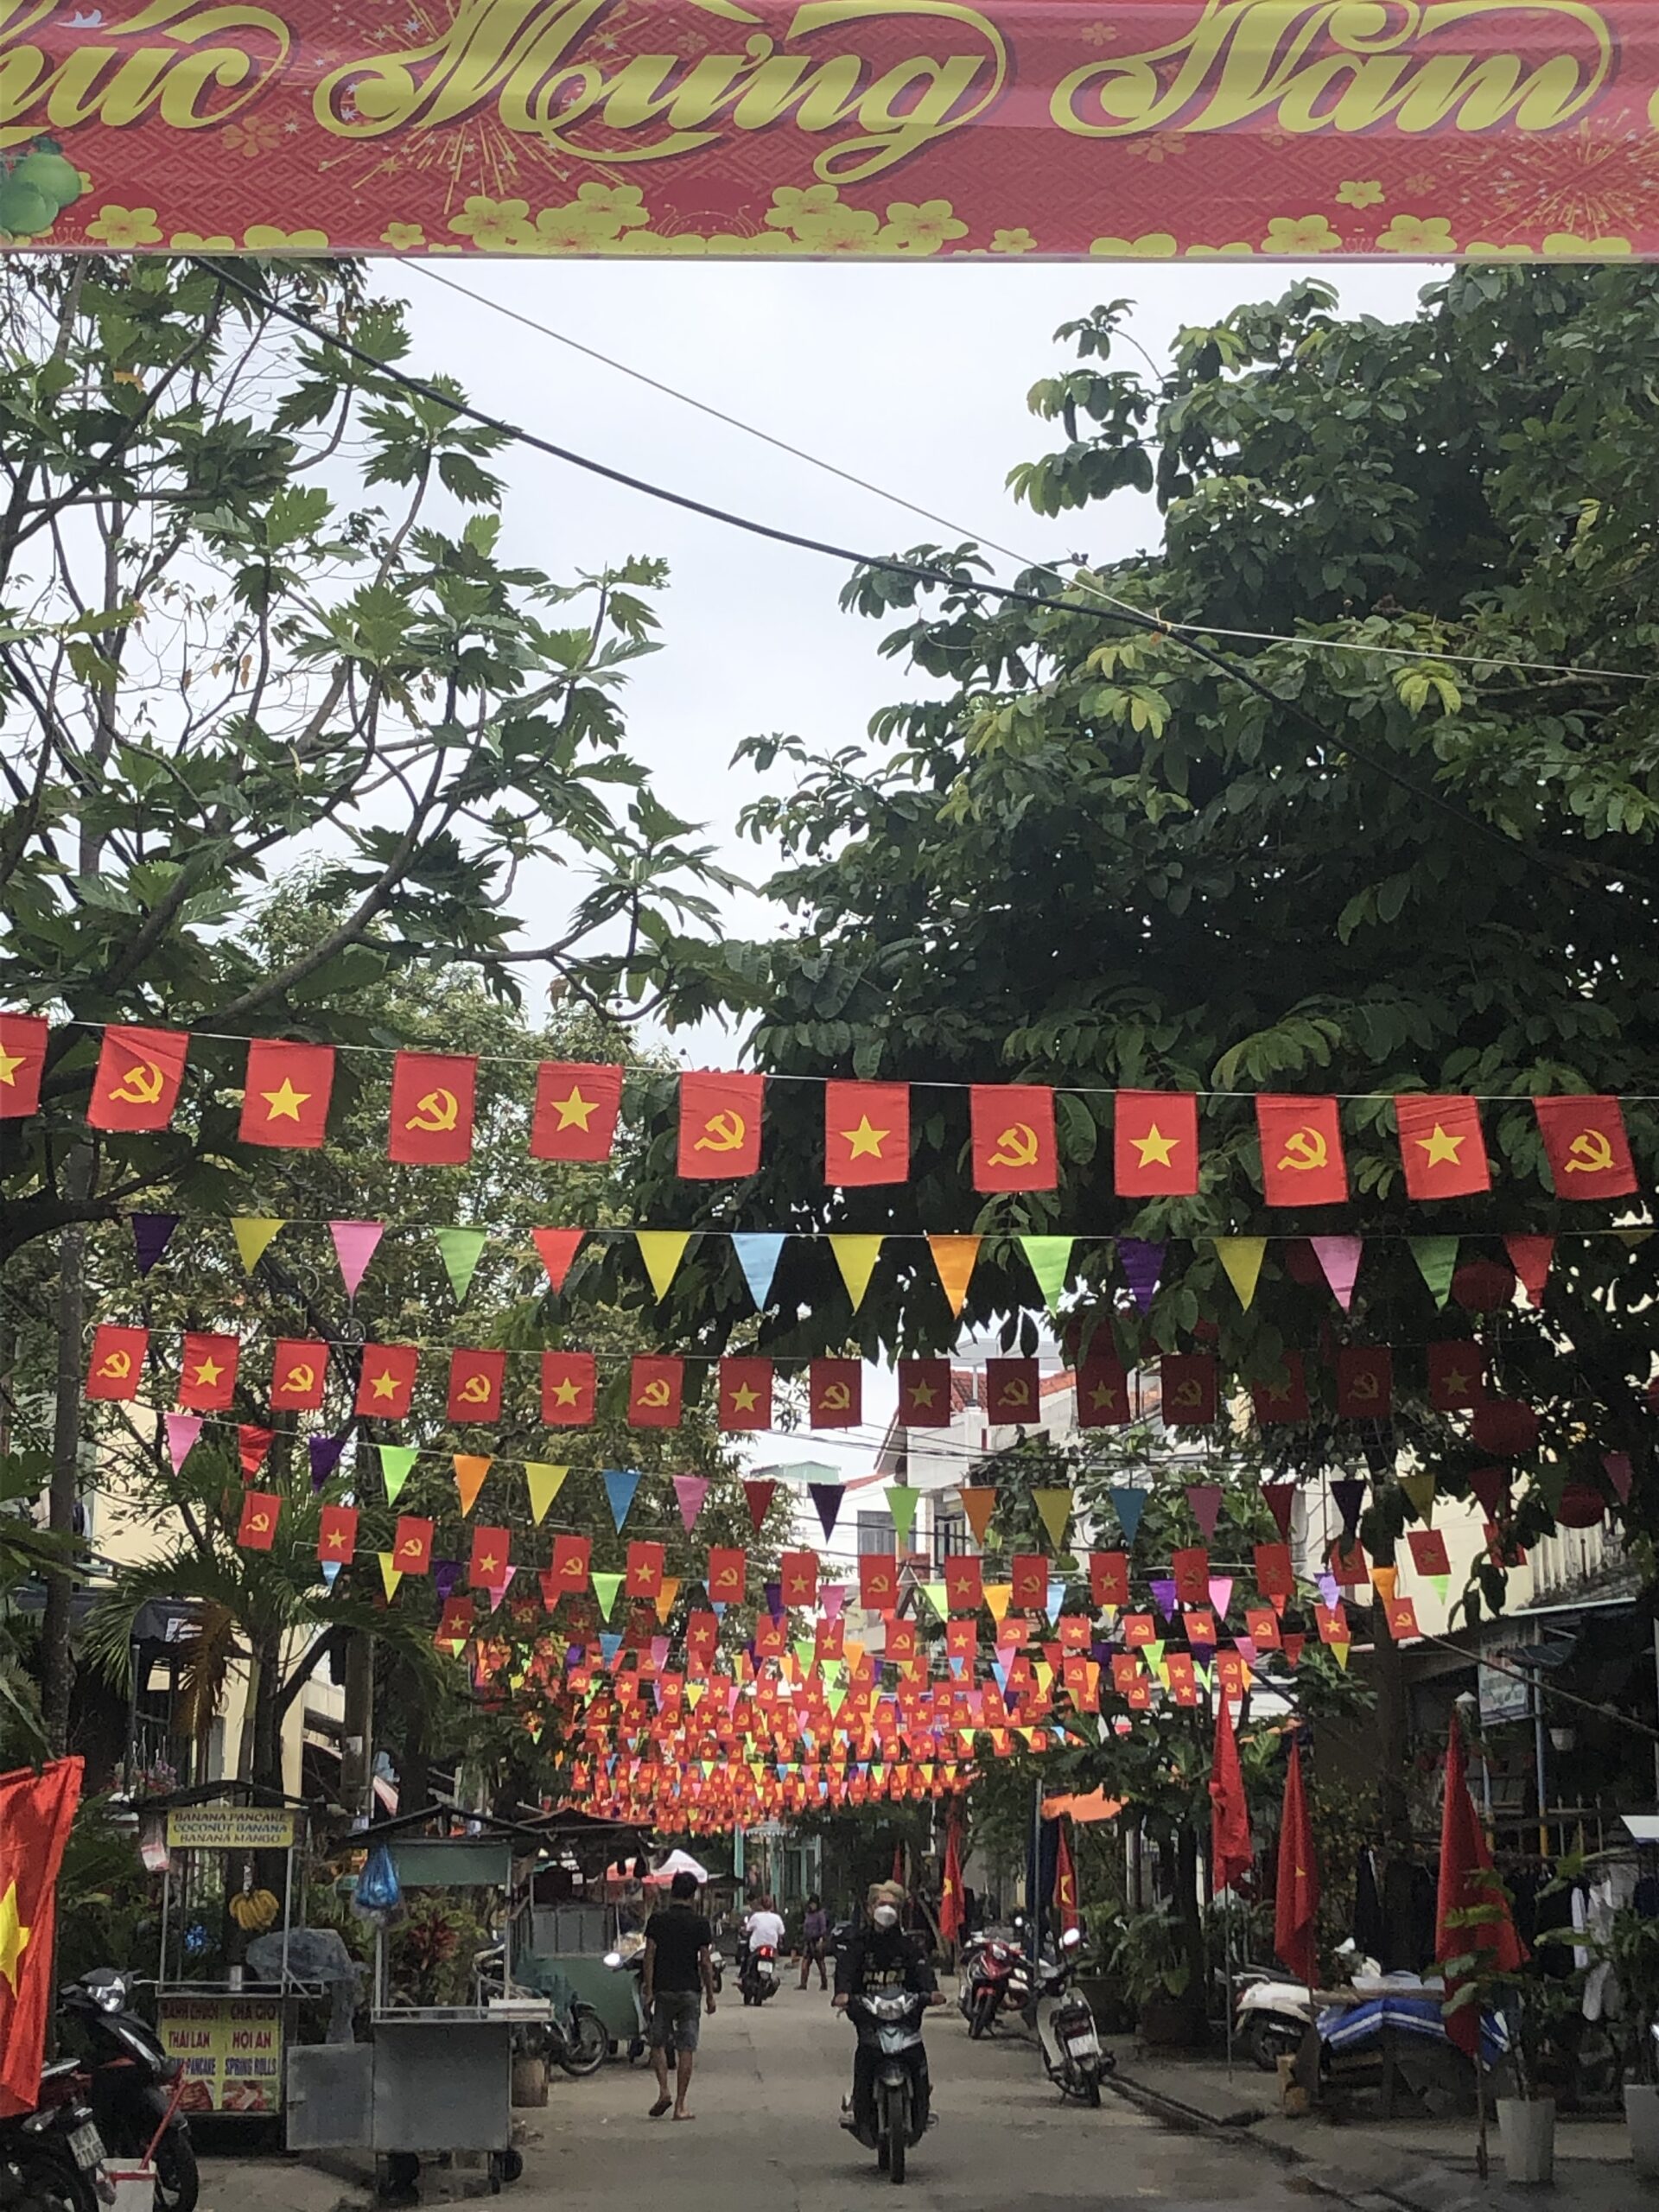
HANOI, VIETNAM – For Laura, 32, and her husband Ethan, 38, the bustling streets of Hanoi offer more than just world-class street food and a vibrant culture; they provide a fiscal sanctuary. Living as expatriates for the past two years, the couple has leveraged a high-income, low-cost-of-living environment to build a net worth of approximately $235,000. However, as they look toward a future return to their hometown of Philadelphia, the "expat bubble" is beginning to feel fragile.
The couple’s story is a modern case study in "geoarbitrage"—the practice of earning in a strong currency while living in a region with a significantly lower cost of living. Yet, as they prepare for the transition back to the American economy, they face a complex set of financial dilemmas: stagnant retirement contributions, a fear of domestic inflation, and a profound psychological aversion to debt born from a grueling history of student loan repayments.

Main Facts: The Expat Equilibrium
Laura and Ethan’s current financial status is characterized by high liquidity and a debt-free balance sheet. Ethan, an English literature teacher at an international school, earns a gross annual salary of $74,442. While this might be a middle-class wage in the United States, in Hanoi, it is a small fortune. His expat package includes fully covered rent and annual flights home, effectively eliminating two of the largest hurdles to wealth accumulation.
Laura, formerly a software engineer for a Philadelphia non-profit, is currently a full-time graduate student. She is pursuing a Master’s in Public Health with a focus on Maternal and Child Health, an endeavor she is funding out-of-pocket to avoid new debt.
Key Financial Indicators:
- Total Assets: $235,708
- Cash on Hand: $104,370 (Liquid savings and checking)
- Retirement Savings: $112,555
- Debt: $0
- Monthly Expenses: $1,741 (Inclusive of tuition, travel, and lifestyle)
Despite these healthy numbers, the couple reports significant "financial anxiety." Their concerns center on the "opportunity cost" of their current lifestyle, the looming high interest rates of the U.S. mortgage market, and the fact that they have not contributed to a retirement account in nearly 24 months.

Chronology: From Debtors to Global Citizens
The couple’s financial journey began in Philadelphia, where they faced a combined student loan burden of $140,000. Their early years together were defined by a radical commitment to debt elimination.
- 2018–2019: Ethan makes the final payment on $80,000 of student debt. Inspired by his progress, Laura pivots from "squirrel hoarding" (saving without addressing debt) to an aggressive repayment strategy.
- 2020: Laura pays off $60,000 in student loans in just 11 months, achieving total debt freedom for the household.
- 2021: The couple relocates to Hanoi for Ethan’s teaching position. Laura begins working as a software engineer in the city.
- 2022: Ethan completes an accelerated Master’s in Education for a net cost of $4,000. Laura begins her MPH program.
- 2023: Laura resigns from her contract work to focus on her degree. The couple spends the year traveling extensively across Southeast Asia, visiting Indonesia, South Korea, Thailand, and Japan, while maintaining a high savings rate.
- Future (2025 and beyond): The couple plans to return to the U.S. to buy a home and start a family, a move that triggers their current fiscal apprehension.
Supporting Data: The Cost of Living Gap
The primary driver of the couple’s anxiety is the stark contrast between their current expenditures and the projected costs of a U.S. lifestyle. In Hanoi, their lifestyle is luxurious by local standards yet costs a fraction of a Philadelphia budget.

Current Monthly Expenditure Breakdown (USD)
| Category | Cost | Notes |
|---|---|---|
| Rent | $0 | Covered by employer |
| Groceries | $250 | Includes household supplies and alcohol |
| Dining/Cafes | $150 | Local meals cost as little as $0.75 |
| Travel | $250 | High frequency, low-cost regional flights |
| Tuition | $700 | Laura’s MPH (temporary expense) |
| Health/Gym | $50 | High-quality bouldering and yoga |
| Utilities/Misc | $341 | Water, electric, internet, and incidentals |
| Total | $1,741 |
In Philadelphia, a comparable lifestyle—including a mortgage on a median-priced home ($350,000+), car insurance, health insurance premiums, and American grocery prices—could easily quadruple these monthly expenses. This "reverse culture shock" in pricing is the root of Laura’s desire to pay for a home in cash, a strategy that would require saving upwards of $400,000 in liquid capital.
Official Responses: Expert Financial Analysis
Elizabeth Thames, a financial consultant known as "Mrs. Frugalwoods," reviewed the couple’s case and provided a strategic roadmap. Her analysis challenges the couple’s "debt-averse" instincts, suggesting that their fear of mortgages might actually be detrimental to their long-term wealth.

1. The "Cash for House" Fallacy
Thames argues that paying cash for a home is often an emotional decision rather than a mathematically sound one. "A paid-off house returns the rate of your mortgage interest," Thames explains. If a mortgage is 6% but the stock market historically returns 7–10%, the "opportunity cost" of tying up $400,000 in a house is significant. Furthermore, real estate is an illiquid asset; you cannot easily "sell a bedroom" to pay for emergency medical bills or groceries.
2. Expat Retirement Eligibility
A major point of confusion for Laura and Ethan is whether they can contribute to U.S. retirement accounts while living abroad. According to IRS guidelines and H&R Block expat specialists, the ability to contribute to an IRA depends on whether the couple has "earned income" leftover after claiming the Foreign Earned Income Exclusion (FEIE). If their entire income is excluded from U.S. taxes, they are ineligible to contribute to an IRA. Thames recommends a "Spousal IRA" for Laura once she returns to work or if Ethan has non-excluded income.

3. Pension and Portfolio Optimization
The couple’s retirement portfolio is currently fragmented across several old 401(k) and 403(b) accounts.
- The Recommendation: Rollover these disparate accounts into a single Traditional or Roth IRA to gain control over investment choices and reduce fees.
- The Pension Factor: Ethan has a $20,692 stake in the Pennsylvania Public School Employees’ Retirement System (PSERS). Thames urges the couple to contact a union representative to determine if these years of service can be "bought back" or applied to a future teaching position in the U.S., which could be worth hundreds of thousands in lifetime value.
Implications: The Psychological Weight of the Return
The case of Laura and Ethan highlights a growing trend among millennial expats: the "Waiting Room" syndrome. They are in a financial holding pattern—saving aggressively but hesitant to invest because their "home base" is not yet established.

The Problem of "Dead Cash"
With over $100,000 sitting in high-yield savings accounts, the couple is protected against short-term volatility but is losing ground to long-term inflation. While a 3.90% interest rate in a Marcus savings account is respectable, it barely keeps pace with the rising costs of U.S. real estate.
The Transition Strategy
To soften the blow of returning to the U.S., the couple must shift their mindset from "debt avoidance" to "wealth optimization." This includes:

- Accepting Managed Debt: A mortgage can serve as a hedge against inflation, allowing them to keep their capital invested in the market.
- Consolidating for Efficiency: By moving their funds into low-fee total market index funds (like Vanguard’s VTSAX or Fidelity’s FSKAX), they can minimize "expense ratios"—the hidden fees that can strip a portfolio of 20-30% of its value over 30 years.
- Establishing a "Landing Fund": Rather than earmarking all cash for a house, they should designate a specific "Transition Fund" to cover cars, furniture, and the initial high costs of re-establishing a life in Philadelphia.
Conclusion
Laura and Ethan are not "falling behind," despite their anxieties. Their debt-free status and $235,000 net worth at ages 32 and 38 put them well ahead of the average American household. However, the transition from a low-cost expat life to a high-cost domestic life requires more than just a large savings account; it requires a sophisticated investment strategy that accounts for inflation, liquidity, and the power of compound interest.
As they enter their final year in Hanoi, the couple’s challenge will be to stop "hoarding" and start "deploying" their capital in a way that serves their 10-year vision of a stable, child-filled home in the United States.