From Livestock to Ledgers: How a Vermont Family is Pioneering Early Financial Literacy
The annual county fair in Vermont is traditionally a celebration of agriculture, community, and local heritage. However, for one family, the "Frugalwoods," it recently served as a high-stakes laboratory for a different kind of harvest: financial literacy. By utilizing the fair’s "panorama of consumerism" as a teaching tool, parents are finding innovative ways to instill complex economic concepts in children as young as five and seven years old.
The following report analyzes the methodologies, psychological implications, and educational frameworks used by these parents to demystify the "weird adult world of money," transforming every-day interactions into a scaffolded curriculum on labor, debt, and discretionary spending.
1. Main Facts: The "Family Money Philosophy"
At the heart of this educational experiment is a clearly defined "Family Money Philosophy." Unlike many households where financial boundaries are opaque or reactive, the Frugalwoods model establishes a rigid line between parental obligations and child-led discretionary spending.
The Boundary of Responsibility
The parents provide for all "essential" needs, which include:

- Infrastructure and Survival: Housing, healthcare, and a nutritious diet.
- Education and Enrichment: Books from libraries/used sales, museum admissions, and fair entry fees.
- Social and Physical Well-being: Clothing and basic toys.
The Discretionary Tier
The children, ages five and seven (referred to as Kidwoods and Littlewoods), are responsible for funding "extras" through their own earned capital. This includes:
- Specialty Foods: While the parents pay for a restaurant meal, the children must pay for their own dessert.
- Souvenirs: Any trinkets or toys from gift shops or fairgrounds.
- The Scholastic Book Fair: While the home is filled with books, the "novelty" of a school book fair catalog is treated as a luxury purchase.
By compartmentalizing spending in this manner, the parents remove the emotional friction of "begging" for toys. The answer is never "no" based on whim; it is "yes, if you have the funds."
2. Chronology: From Basic Chores to the "Unicorn Debt" Crisis
The development of the children’s financial acumen has followed a specific chronological progression, moving from the simple understanding of labor to the complex reality of interest and debt.
Phase I: The Labor-Capital Link (Ages 4-6)
The process began with the introduction of "paid chores." The family distinguishes between Daily Unpaid Work (contributions to the household like making beds, clearing the table, or collecting eggs) and Market-Value Chores (tasks that benefit the family unit as a whole).
Paid chores, such as organizing kitchen cabinets or cleaning out the family vehicle, are negotiated at "fair market value." This phase taught the children that money is a finite resource derived from effort. A recent $10 lump-sum contract for a full kitchen reorganization demonstrated the eldest child’s growing ability to negotiate "chore bundles."
Phase II: The "Unicorn Debt" (The Turning Point)
A pivotal moment in the curriculum occurred during a previous year’s county fair. Kidwoods sought to purchase an inflatable turquoise unicorn priced at $13, but she only possessed $9. In a calculated move, her parents allowed her to enter into a debt agreement, lending her the remaining $4.
The subsequent weeks were a "visceral lesson" in the burden of credit. Kidwoods was required to perform chores to pay back the $4, but she experienced no new "reward" for that labor, as the unicorn had already been consumed. Her realization—"It is not fun to do chores to earn money for something I’ve already bought"—marked a transition from simple spending to an understanding of the psychological cost of debt.
Phase III: Independent Logistics (Current Phase)
The most recent stage involves "Logistical Responsibility." The children are now responsible for:
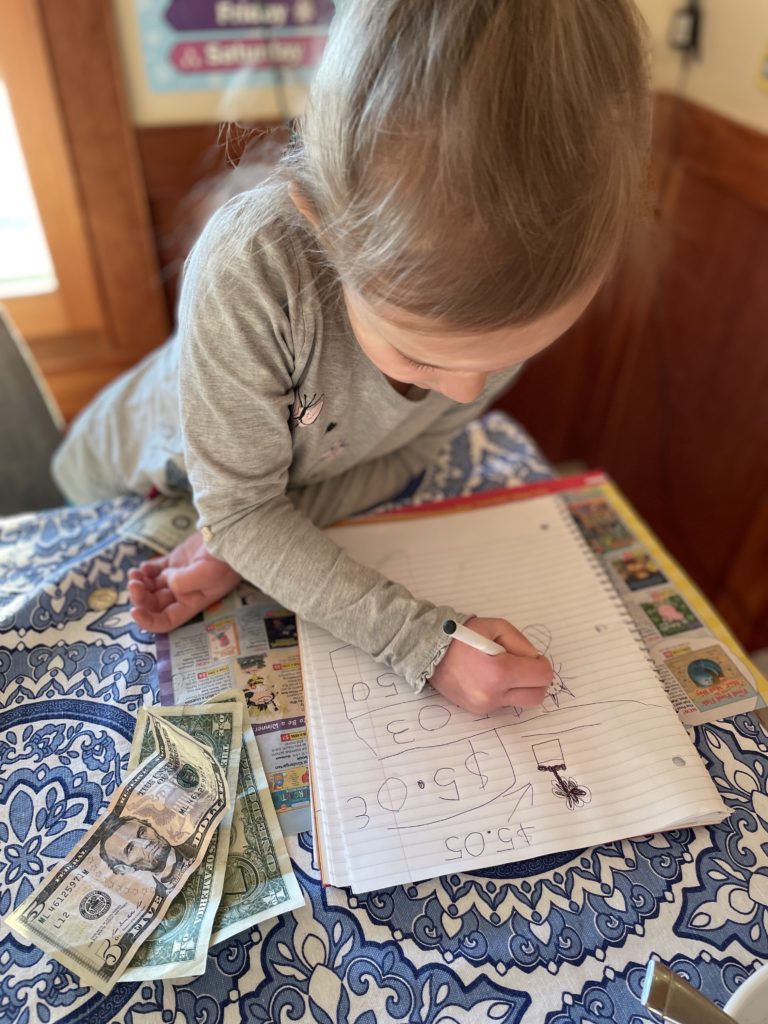
- Asset Management: Carrying their own wallets and purses.
- Planning: Deciding in advance if they need to bring money to an event.
- Transaction Execution: Approaching cashiers, asking prices, and counting out change independently.
3. Supporting Data: The Case for Early Intervention
The Frugalwoods’ approach aligns with significant psychological and economic research regarding childhood development.
The "Age Seven" Milestone
A landmark study by the University of Cambridge found that many of the habits that will help or hinder financial health in later life are formed by the age of seven. By this age, children can typically grasp the concept of "delayed gratification" and understand that money can be exchanged for goods. The Frugalwoods’ focus on children aged five and seven targets this critical window of cognitive development.
The Friction of Cash
Research suggests that using physical cash—as the Frugalwoods children do—creates more "pain of paying" than using digital methods. For a child, watching three five-dollar bills leave their hand for a $15 toy provides a concrete understanding of loss that a credit card swipe cannot replicate.
Comparative Chore Values
In the Frugalwoods household, chore rates are not arbitrary. They are designed to reflect the effort required:
- Low Complexity ($0.50 – $1.00): Emptying small trash cans, matching socks.
- High Complexity ($2.00 – $10.00): Organizing deep storage, seasonal yard work.
4. Official Perspectives: The Educational Rationale
While the Frugalwoods’ method may seem rigorous to some, it is rooted in a philosophy of "demystification."
The Parental Statement
The parents argue that avoiding the topic of money creates anxiety rather than protecting children. "Kids don’t go around thinking about the fact that adults are paid to do their jobs," the mother notes. "By breaking down this equation, we’re working to demystify and simplify this weird adult world. It removes judgment, bias, and stress."
Expert Analysis: The "Labor vs. Allowance" Debate
Financial educators often split into two camps: those who support a "pure allowance" (to teach budgeting) and those who support "paid chores" (to teach the work ethic).
Dr. David Whitebread, a developmental psychologist, suggests that the most effective models combine elements of both. The Frugalwoods model leans heavily toward the "earned income" model, which experts say is particularly effective at teaching "Self-Regulation." When a child decides not to buy a $7 cupcake because they know it represents an hour of trash-collecting, they are practicing high-level executive function.
5. Implications: Long-Term Economic Resilience
The Frugalwoods are not merely teaching their children how to buy toys; they are building a framework for adult economic survival.
Avoiding the "Debt Trap"
By allowing the "Unicorn Debt" crisis to happen at age six over a $4 loan, the parents have likely inoculated the child against much larger mistakes in adulthood. The "visceral" feeling of working for a past purchase is a memory that can prevent future credit card mismanagement.
Money as a Neutral Tool
One of the most significant implications of this method is the decoupling of money from emotion. In this household, money is taught as a "tool," similar to exercise or sleep. It is not a measure of self-worth or status. This mindset is critical in preventing the "conspicuous consumerism" that often leads to financial instability in the middle and upper classes.
The Future: The "Bank of Parental Units"
The next phase of the family’s plan involves introducing The Bank of Parental Units, a home-based savings account that pays a high internal interest rate. This will transition the children from "Earners/Spenders" to "Investors."
By incentivizing the children to keep their money in the "bank" rather than their wallets, the parents will introduce the concept of Compound Interest. For a seven-year-old, seeing their $20 grow to $22 simply by not spending it is the final piece of the financial literacy scaffold.
Conclusion
The Frugalwoods’ experiment in Vermont suggests that children are capable of handling far more economic complexity than society usually grants them. Through a combination of clear boundaries, real-world consequences, and the dignity of earned income, these parents are preparing the next generation to view money not as a source of stress, but as a manageable tool for a well-lived life. As the girls move from buying fairground desserts to managing interest-bearing accounts, they are not just learning to count; they are learning to thrive.