From Hanoi to Home: Navigating the Financial Complexities of the American Expat Return
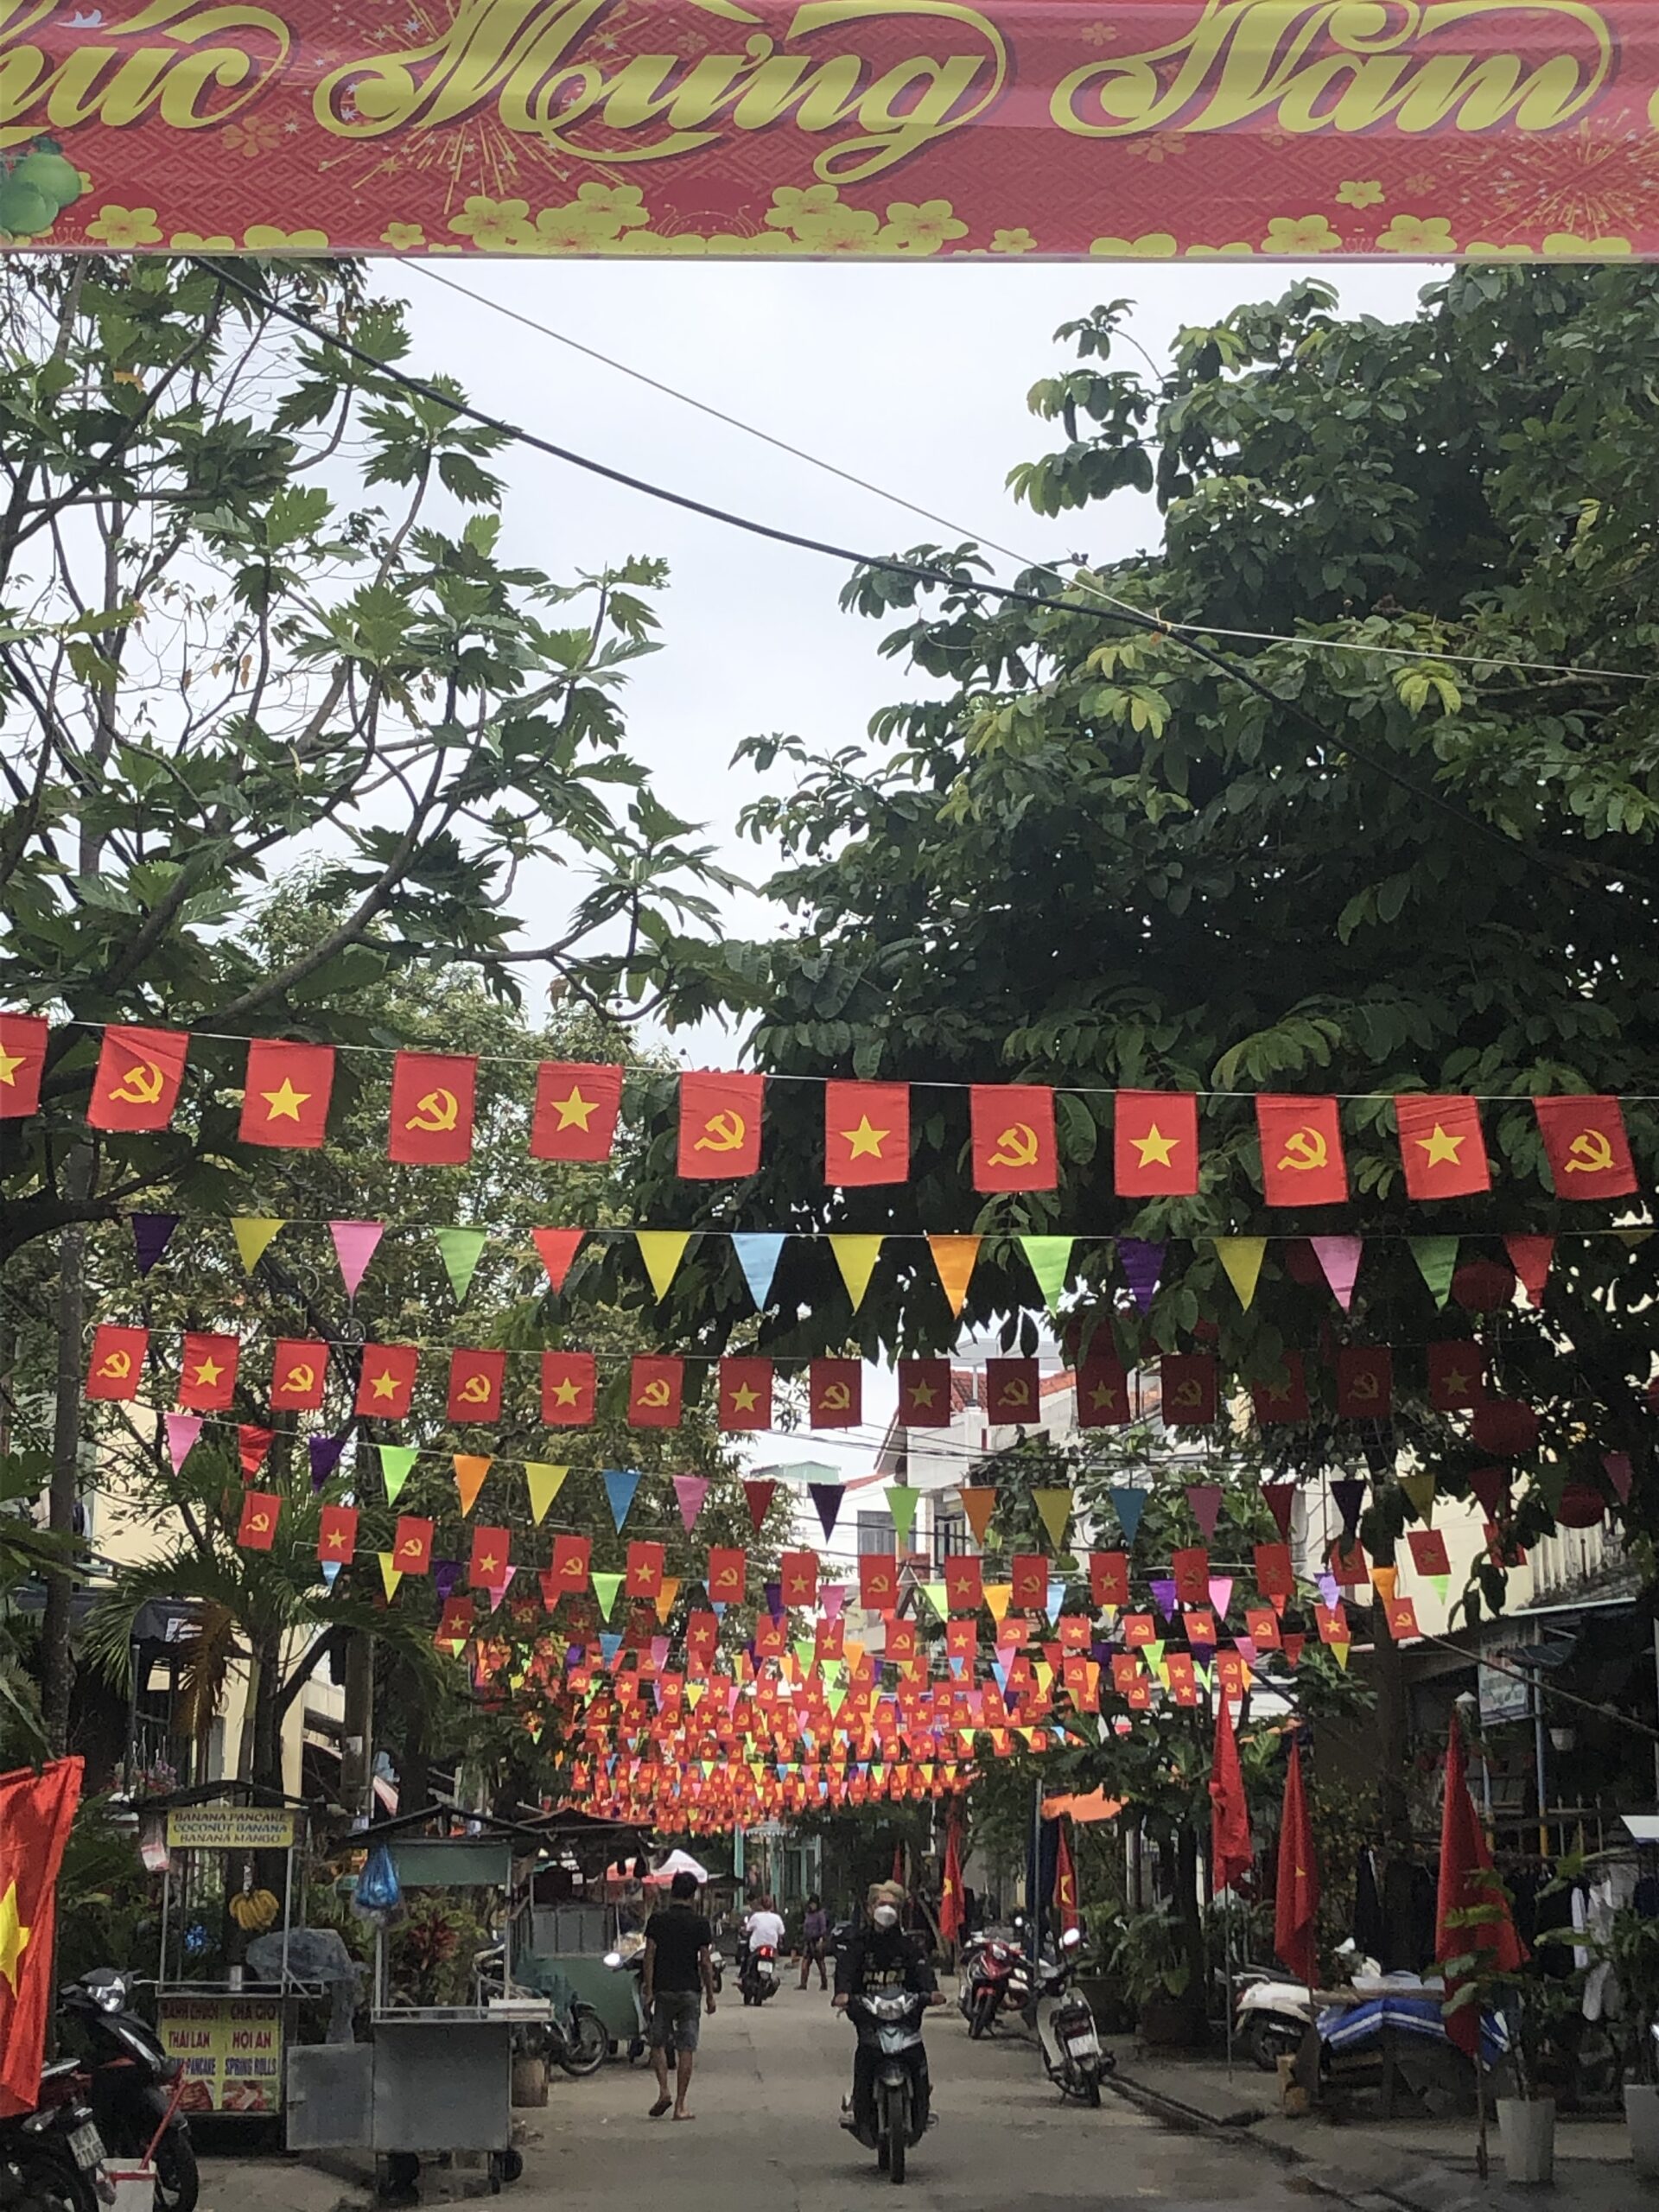
For many Americans, the dream of living abroad involves a romanticized escape from the "rat race"—a world of lower costs, cultural immersion, and professional adventure. For Laura, 32, and her husband Ethan, 38, this dream became a reality two years ago when they traded the streets of Philadelphia for the vibrant, scooter-filled landscape of Hanoi, Vietnam. However, as they look toward a future return to the United States, the couple faces a daunting financial puzzle: how to transition from a low-cost-of-living environment back into an American economy defined by high interest rates, skyrocketing housing costs, and the looming necessity of retirement security.
The following analysis explores the financial trajectory of Laura and Ethan, examining their aggressive debt-clearing past, their current "holding pattern" in Southeast Asia, and the strategic expert advice required to ensure their "reverse culture shock" isn’t a fiscal catastrophe.

I. Main Facts: The Expat Paradox
Laura and Ethan represent a specific demographic of the American workforce: the highly disciplined, debt-averse "global nomad." Currently, the couple lives in Hanoi, where Ethan serves as an English literature teacher at a prestigious international school. His compensation package is a cornerstone of their financial stability, providing not only a competitive salary but also covering their rent and annual flights back to the U.S.
This arrangement has allowed the couple to live on approximately $1,741 per month while maintaining a high quality of life. In Hanoi, their favorite vegetarian meal costs roughly $2.00, and a bowl of pho is less than a dollar. Meanwhile, Laura has utilized this period of low overhead to pivot her career, moving away from software engineering to pursue a full-time Master’s in Public Health (MPH).
Despite their current comfort, a sense of "financial vertigo" has set in. With a total net worth of approximately $235,708, the couple is wealthy by Vietnamese standards but feels vulnerable regarding the American housing market. Their primary concerns center on a two-year hiatus from retirement contributions and a deep-seated fear of debt that has led them to hoard cash—a strategy that experts warn may be counterproductive.
II. Chronology: From Debt-Crushing to Career Pivoting
The couple’s financial journey is defined by two distinct phases: the "Aggressive Repayment" phase in Philadelphia and the "Exploratory Accumulation" phase in Hanoi.

2018–2021: The Philadelphia Clean Slate
Before moving abroad, Laura and Ethan engaged in a Herculean effort to clear their names of student debt. Shortly after they began dating, Ethan made his final payment on $80,000 in loans. Inspired by his discipline, Laura attacked her own debt, paying off $60,000 in just 11 months. This period cemented a "debt-averse" psychology that dictates their current behavior; having felt the weight of $140,000 in combined debt, the prospect of a 30-year mortgage is viscerally unappealing to them.
2021–2023: The Hanoi Transition
The move to Vietnam was a strategic play to lower expenses and allow for professional growth. Ethan secured his Master’s in Education for a mere $4,000 out-of-pocket, thanks to professional development subsidies. Laura, meanwhile, left her non-profit software role to return to her passion: maternal and child health.

During their two years in Hanoi, they have traveled extensively through Indonesia, South Korea, Thailand, and Japan. However, this period of "freedom" has also been a period of retirement stagnation. Because they are living abroad and Laura is currently a full-time student, their contributions to U.S.-based tax-advantaged accounts have largely ceased.
III. Supporting Data: The Balance Sheet
To understand the couple’s dilemma, one must look at the concentration of their assets. Their current financial standing is robust but heavily skewed toward liquidity.

Asset Distribution
| Asset Category | Amount | Percentage of Total |
|---|---|---|
| Cash (Savings/Checking) | $104,370 | 44.3% |
| Retirement Accounts | $112,555 | 47.7% |
| Taxable Brokerage | $18,783 | 8.0% |
| Total Net Worth | $235,708 | 100% |
Income and Expenses
Ethan’s gross annual salary stands at $74,442. While this would be a middle-class wage in Philadelphia, the "expat multiplier" in Vietnam makes it highly lucrative. After taxes and insurance, his monthly take-home is $2,990. Given their monthly expenses of $1,741, the couple is able to save over $1,200 per month even with Laura not working.
However, the data reveals a significant "leakage" in their investment strategy. Much of their $112,555 in retirement is scattered across old 401(k) and 403(b) accounts from previous employers, often in funds with unknown fee structures (expense ratios). Furthermore, their $104,370 in cash is earning a modest 3.90% in a High-Yield Savings Account (HYSA)—a rate that currently struggles to outpace U.S. inflation and pales in comparison to historical stock market returns.

IV. Official Responses: Expert Financial Consultation
Elizabeth Thames, known professionally as "Liz Frugalwoods," provided a comprehensive consultation to address the couple’s anxieties. Her recommendations challenge the couple’s debt-averse instincts, suggesting that their fear of a mortgage might actually be their greatest financial risk.
1. The "Cash for a House" Fallacy
The most striking element of Laura and Ethan’s plan is the desire to save enough cash to buy a home outright. Thames argues this is a "massive opportunity cost."

- The Math: A mortgage acts as an inflation hedge. If a couple borrows at 6% but the stock market averages 7–8% over the long term, the "spread" favors the investor.
- Liquidity Risk: Thames warns that a paid-off house is an "illiquid asset." You cannot eat a kitchen cabinet or use a roof to pay for an emergency surgery. By tying up $300,000+ in a physical structure, the couple loses the flexibility that $300,000 in a brokerage account would provide.
2. The Expat IRA Dilemma
A common confusion for Americans abroad is whether they can contribute to an IRA. Thames clarifies that eligibility depends on "earned income" that is not excluded by the Foreign Earned Income Exclusion (FEIE).
- The Strategy: If Ethan’s income exceeds the FEIE limit, or if they choose not to exclude it all, they can contribute. Since Laura has no earned income, she is eligible for a Spousal IRA, provided Ethan has enough qualifying income to cover both contributions.
3. Consolidation and Fee Management
Thames recommends a "cleanup" of their retirement portfolio.

- Rollovers: The couple should roll over their disparate 401(k)s and 403(b)s into a single Traditional or Roth IRA. This allows for better control over investment choices.
- Expense Ratios: The couple was unaware of their "expense ratios"—the fees paid to fund managers. Thames notes that even a 1% fee can strip away tens of thousands of dollars over a 30-year horizon. She advocates for low-fee total market index funds (like Vanguard’s VTSAX), which often have fees as low as 0.04%.
V. Implications: The Road Ahead
The case of Laura and Ethan highlights a broader trend among the "FIRE" (Financial Independence, Retire Early) and expat communities: the struggle to balance psychological comfort with mathematical optimization.
The Psychological Hurdle
Laura’s anxiety stems from a lack of "automation." In Philadelphia, their lives were structured by the rhythm of debt payments. In Hanoi, the lack of a clear "next debt" has left them feeling adrift. The implication for their return to the U.S. is that they must redefine their relationship with debt. A mortgage should not be viewed as the "student loan monster" of their 20s, but as a strategic tool for wealth building.

The "Buffer" Strategy
Despite the opportunity cost of cash, Thames acknowledges that for expats in transition, cash is a "security blanket." With the unknowns of moving costs, new car purchases, and potential periods of unemployment during the move back to the U.S., maintaining a six-figure cash buffer is not "optimal" for growth, but it is "optimal" for sleep.
Career Trajectory
The final piece of the puzzle is Laura’s MPH. Upon her return, her earning potential in public health, combined with her previous software engineering background, could significantly accelerate their "catch-up" phase for retirement. The transition from a one-income household in a low-cost country to a two-income household in a high-cost country will require a disciplined "lifestyle creep" defense.

Conclusion
Laura and Ethan are not "falling behind" in the traditional sense; they are merely in a period of strategic redirection. By consolidating their retirement accounts, lowering their investment fees, and accepting a mortgage as a rational financial instrument rather than an emotional burden, they can successfully bridge the gap between the easy life in Hanoi and the stable, family-oriented future they desire in the United States. Their story serves as a blueprint for other expats: the key to returning home is not just having enough money, but having that money in the right places.